Subscribers Only Content
High resolution image downloads are available to subscribers only.
Not a subscriber? Try one of the following options:
OUR SERVICES VISIT CAGLE.COMFREE TRIAL
Get A Free 30 Day Trial.
No Obligation. No Automatic Rebilling. No Risk.
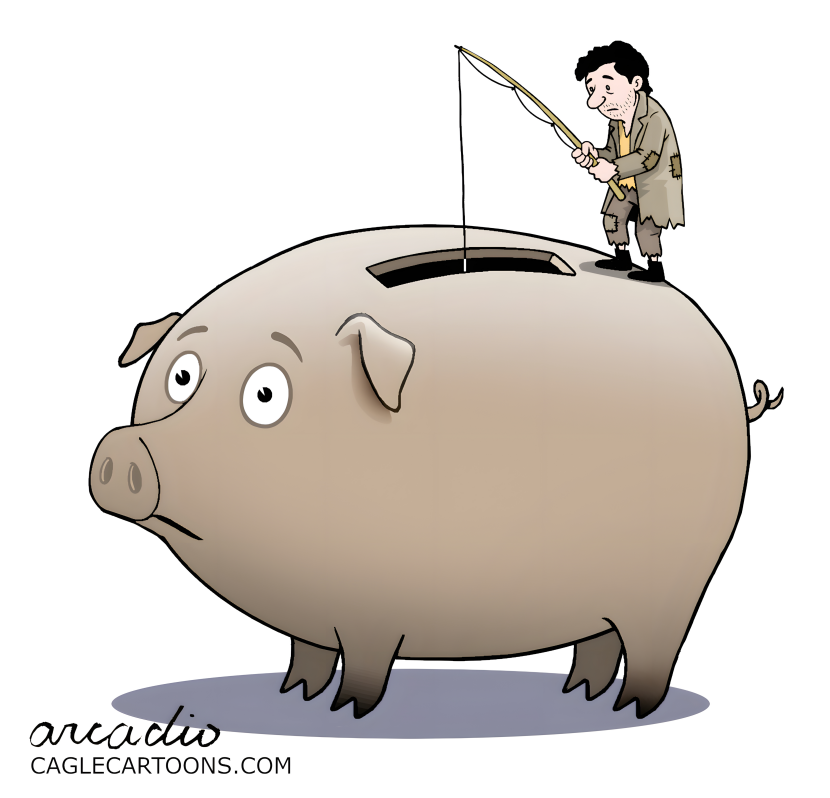
Left-wing advocacy groups and Democratic state attorneys general are urging federal regulators to block the bank charter applications of fintech lenders that want to acquire banks.
Their goal is to advance an ideological anti-private-lending agenda, but regulators should defer questions of policy to Congress and judge the pending applications solely on traditional criteria of whether the entities are qualified.
The leader of this effort is the Center for Responsible Lending, a left-wing political advocacy group co-founded and funded by Herb and Marion Sandler. The Sandlers made their fortune by selling negative amortization mortgages the New York Times called the “Typhoid Mary of the Mortgage Industry.” They sold their portfolio to Wachovia Bank. It was a ticking time bomb that destroyed Wachovia.
The group advocates restrictions and limitations on lenders whose business practices differ from those of its own affiliated Self-Help Credit Union. It advances an ideological agenda of ever-greater government control of capital. Somehow, these are supposed to be the good guys?
Historically, the Center for Responsible Lending argued tnon-bank providers operated under a “rent-a-bank scheme” that created “an unlevel playing field and a significant risk that consumer protection issues affecting vulnerable consumers will go undetected.” But now that these companies accepted their challenge and want to become banks, including subjecting themselves to all of the additional regulatory scrutiny that that entails, they object to that too. Opposing both the partnership model and its alternative shows that the objection is to the lending itself, not to the form of the lender. That is a policy argument that should be taken to Congress, not imposed as a charter condition.
The statutes set clear tests: capital, managerial resources, and financial stability. Those are the criteria Congress established. These activists and state officials are effectively demanding rate caps be injected into this process, even though Congress has been clear regulators cannot impose them. Allowing rate caps to be set through the bank charter process thwarts the will of Congress.
Moreover, rate caps have been tried and failed. When Illinois adopted a 36 percent all-in cap, loans to subprime borrowers fell 38 percent. Average loan size to subprime borrowers rose 35 percent. Survey evidence showed worsened financial well-being among borrowers who lost access. In that survey, only 11 percent of borrowers reported improved well-being after the cap, and 79 percent wanted the option to return to their prior lender. The cap did not make loans cheaper. It made them less available.
Credit markets respond to price controls by rationing. The borrowers with the weakest credit are the first to be cut off. Advocates then treat the resulting gaps as proof that still more restriction is needed. The cycle continues until legal credit is driven further underground. Many of the activists would be happy to eventually destroy the viability of private consumer lending and replace it with a government program.
Federal bank regulators have a defined job. They are charged with determining whether applicants meet the statutory tests. They are not charged with deciding whether non-prime lending should exist, how much of it should exist, or at what price. Those are policy questions for Congress.
I don’t know whether the bank charter applications of fintech lenders should be approved. I do know that the decision should be made on the statutory criteria alone, and regulators should ignore the noisy pressure campaign from the Center for Responsible Lending and its allies.
–
Copyright 2026 Phil Kerpen, distributed by Cagle Cartoons newspaper syndicate.
Phil Kerpen is the president of American Commitment and the author of “Democracy Denied.” Kerpen can be reached at [email protected].